On Wednesday, December 9, 2026, at 2:00 PM ET (20:00 CET), the Federal Reserve releases two documents at the same minute: the policy statement and the Summary of Economic Projections (SEP). In 2026, four of the eight scheduled meetings, in March, June, September and December, come with the SEP, and those are the meetings where NQ most often moves on something other than the rate decision itself. The day's timeline, from the blackout period to the minutes, is in the FOMC day post; this one is about the projections.
What the SEP contains
Every Fed participant, voting or not, is invited to submit a projection; 18 did in June and September 2026, because Chair Warsh doesn't submit one. The SEP publishes the median, the central tendency and the full range for five variables:
| Variable | What it projects |
|---|---|
| Real GDP growth | Fourth quarter over fourth quarter |
| Unemployment rate | Average for the fourth quarter |
| PCE inflation | Fourth quarter over fourth quarter |
| Core PCE inflation | The same, excluding food and energy |
| Federal funds rate | Each participant's appropriate rate at the end of each year |
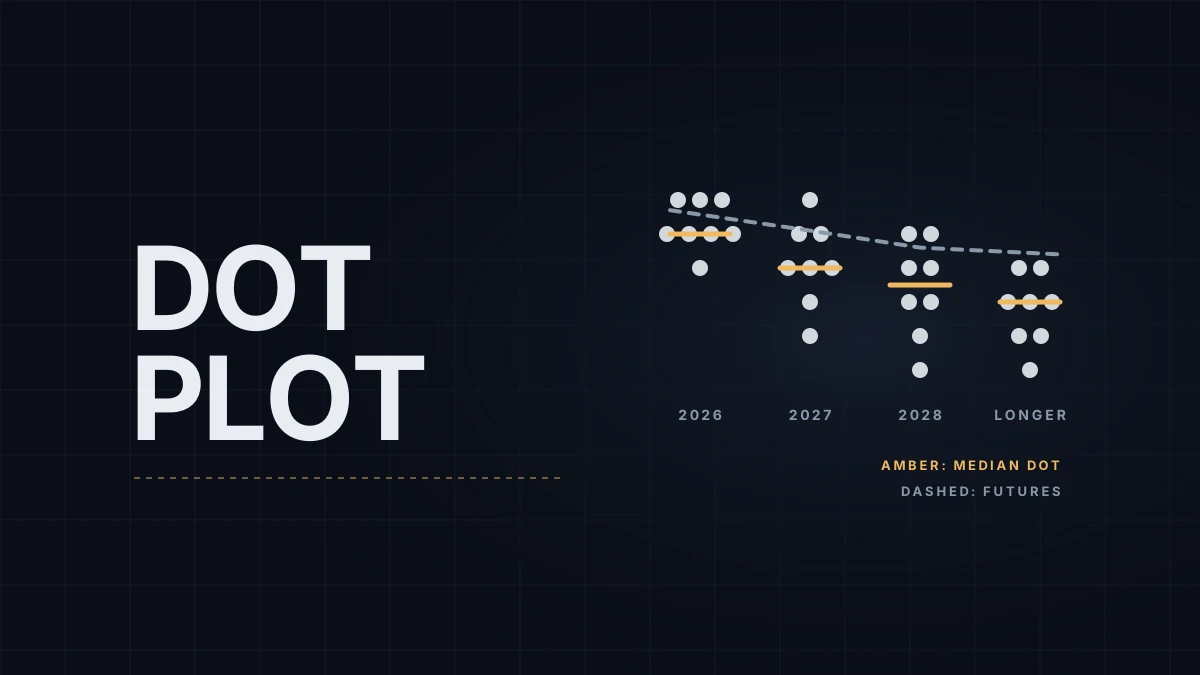
Each variable covers the current year, the next two or three years and the "longer run." The last row is the famous chart: one dot per participant per year, anonymous, so the December 2026 chart shows where each participant (up to 19: 7 governors and 12 Reserve Bank presidents) thinks the rate should be at the end of 2026, 2027, 2028 and 2029, and over the longer run.
Why NQ reacts to the gap, not the dots
By the time the SEP comes out, fed funds futures already price a rate path; CME's FedWatch tool turns those prices into probabilities. The market moves on the difference between that path and the median dot, usually for the coming year.
A hypothetical: futures price three quarter-point cuts in 2027 and the median dot shows two. That's a hawkish surprise. Two-year Treasury yields tend to rise first, because they track expected policy most closely, and NQ tends to fall, because Nasdaq-100 companies are valued on profits far in the future and a higher expected rate lowers what those profits are worth today. The same mechanism is behind the yield sensitivity covered in the Treasury auctions post. If the median shows four cuts instead, the direction reverses. Nothing about the rate decision itself has to change for either move.
The longer-run dot matters too. It is the committee's estimate of the neutral rate, the level that neither speeds up nor slows down the economy, and a higher longer-run median raises the floor under every future cut.
In points, the move can be large. At $20 per point on NQ (the tick and point value guide has the arithmetic), a 100-point swing between 2:00 and 2:05 PM ET is $2,000 per contract, and SEP days often produce a second swing after 2:30.
The two-step afternoon
At 2:00 PM ET the statement and the SEP land together, so the first reaction mixes the decision, the statement's wording and the dots. At 2:30 PM ET (20:30 CET) the Chair's press conference starts, and the Chair often comments on the dots directly, for example by stressing that participants aren't bound by them. That commentary can reverse the first move. The minutes, released about three weeks later (December 30 for this meeting), sometimes explain how wide the disagreement behind the dots was.
How not to overread the dots
- A dot isn't a vote. Each participant writes down what they think is appropriate given their own forecast. Non-voting presidents submit dots too, and the rotation of voting presidents changes every January.
- The median is fragile. With 19 participants it's the tenth dot; with 18, as in September 2026, it's halfway between the ninth and the tenth. One person moving a quarter point can shift it, so look at how many dots sit at each level, not only where the median landed.
- The far years are guesses. The 2029 and longer-run dots move with each meeting's mood more than with new data.
- The economy comes first. If the inflation projections rise, the dots rising with them is consistent, not a change of heart. The surprise is a higher rate path with unchanged inflation.
Traders handle SEP afternoons in the same three ways as any FOMC day: flat through it, fading the first move, or following a break after the press conference. The FOMC day post compares them. Whatever the plan, size it for two moves rather than one, and remember that 2:00 PM ET is 20:00 in most of Europe.
Educational content, not investment advice. Futures trading involves substantial risk of loss. Examples are for illustration only. Read the full Risk Disclosure.